Published · Updated
Deregistration, as used here, means applying under Hong Kong’s Companies Ordinance to remove an eligible local company from the register and dissolve it after the statutory process. It is not a temporary suspension, the Registrar’s power to strike a company off the register, or winding-up. For shareholders and decision-makers managing a Hong Kong company from Taiwan, start by confirming eligibility, resolving the company’s responsibilities and assets, and assigning someone to track each official milestone. The steps described here concern Hong Kong. Company records, tax matters and contracts may also involve other jurisdictions, so confirm the facts for the particular group.
Confirm deregistration eligibility and alternative routes
Only a defunct, solvent local private company or local company limited by guarantee may apply for deregistration, subject to the exclusions in section 749(2) of the Companies Ordinance. The conditions must all be met: every member agrees; the company has never started business or has not operated during the three months immediately before applying; it has no outstanding liabilities; it is not a party to legal proceedings; and neither it nor, if it is a holding company, any subsidiary has assets consisting of immovable property in Hong Kong. The company must also obtain a Notice of No Objection from the Commissioner of Inland Revenue. A lack of recent sales alone does not establish eligibility. A registered non-Hong Kong company cannot use this NDR1 route. A re-domiciled company is generally treated as incorporated in Hong Kong from its re-domiciliation date, but check its current records and applicable requirements. Companies Registry FAQ on deregistration, striking off and winding-up
Before deciding, collect the company’s registration details, articles, members’ register and resolution records. Compare recent transactions, contracts, invoices, bank statements and directors’ records to establish its operating status. Ask all members to confirm their consent and check debts, proceedings, property and the group structure. Mark each item as confirmed, awaiting evidence or not satisfied, with its supporting record, owner and next decision point. In a cross-border group, compare the contracting party and recipient of funds: a Taiwan parent, Hong Kong subsidiary and overseas payment platform should not be treated as one account or entity just because records appear together. Record discrepancies for follow-up rather than treating zero revenue or an inactive management team as proof.
If the company still owes money, operates, is involved in proceedings or holds property, ask a Hong Kong legal or accounting professional to assess the available route. Winding-up is a separate process for settling accounts, liquidating assets and distributing net assets. The Registrar’s striking-off power is also distinct: a company cannot apply to strike itself off as a shortcut. The initial handover should be an eligibility checklist showing the evidence, missing documents, responsible person and next decision for each condition.
Review liabilities, assets, litigation and operating status
Before starting the tax and registry filings, prepare a traceable asset and liability schedule. Include loans, amounts due to shareholders, supplier payables, customer refunds or deposits, payroll and other commitments. List inventory, receivables, securities, vehicles, intellectual property, bank balances and any Hong Kong property held by the company or its subsidiaries. For each item, record the currency, balance, counterparty, date of the information, supporting evidence and person responsible. Mark figures drawn only from old accounts or verbal confirmation as unverified. Reconcile the cut-off dates in the books, bank statements and payment-platform settlements, including pending refunds, fees and transactions still being cleared. Record the basis and proposed treatment of shareholder advances and group balances rather than omitting them because they involve related companies.
Check whether each account, platform, inventory item and contractual right is still held by the company. For a holding company, review subsidiary assets, intercompany balances, guarantees and shared contracts as well as the parent’s own accounts. The Companies Registry says company property must be properly disposed of before applying and specifically gives credit balances in bank accounts as an example. Companies Registry deregistration service page
Classify each item as settled, awaiting disposal or awaiting external confirmation, and attach evidence such as bank statements, platform settlement records, contract termination notices or directors’ resolutions. If you find a debt, unclear ownership, an ongoing transaction or a proceeding, revisit eligibility before filing; do not describe an unchecked matter as cleared. For legal checks, ask the person handling legal correspondence and review court notices, lawyers’ letters, arbitration records and collection documents. No news received is not evidence that no proceedings exist. The schedule should show the cessation date and evidence, liabilities, asset treatment, litigation checks and questions needing professional judgment.
Plan tax clearance and the Notice of No Objection
The Inland Revenue Department’s Notice of No Objection is required before an NDR1 application. Before submitting Form IR1263, assemble evidence that the company has ceased business and will not resume, and that its trading stock, property and securities have been disposed of. File tax returns already issued; meet any obligation to notify the Commissioner in writing if the company was chargeable for a year for which no return was received; pay outstanding tax, business registration fees, fines and related amounts; answer the Department’s enquiries; and resolve any objections or appeals against assessments. IRD guidance on applying for a Notice of No Objection
The IRD lists a non-refundable application fee of HK$270. It normally issues a notification within 21 working days after receiving a valid application and the fee. If tax matters or liabilities remain, the Department will identify them rather than issue the notice. Once they are cleared, the applicant may resubmit using the notification; the IRD says no further fee is payable for that resubmission. The stated processing time applies to this request only. It is not a timetable or approval promise for the whole deregistration process.
Prepare tax filing and payment records, information on asset disposal, IRD correspondence and replies, the status of any objection or appeal, and current company contact details. Follow Form IR1263 and any specific request from the Department on supporting documents. Keep a copy of the form, payment evidence, notices and follow-up submissions, and assign one person to track each outstanding item. Move to NDR1 only after the formal Notice of No Objection has been issued and its company details have been checked; an application receipt or payment record alone does not mean tax matters are cleared.
Track NDR1 and Gazette notices step by step
After receiving the Notice of No Objection, check the company particulars and issue date. Deliver Form NDR1 with the notice to the Companies Registry within three months of the notice’s issue date. The Registry lists a non-refundable fee of HK$420. For a paper filing, submit the original notice; for an electronic filing, provide a certified copy in accordance with the Registry’s instructions. Electronic filing is available through the Registry’s e-Services Portal, or the documents can be delivered in hard copy. Keep the final signed form, the identity of the signatory, the delivery date and proof of receipt. Set a reminder for the deadline; preparation or posting is not proof that the Registry received the filing. Companies Registry deregistration service page; Specified Forms: Form NDR1
Knowingly or recklessly giving the Registrar materially false or misleading information may be an offence. If evidence is missing or a condition is uncertain, resolve it or seek professional advice before the applicant makes a declaration. Companies Registry deregistration service page
A receipt from the Registry is not proof of dissolution. Check the company’s public record and the Gazette. The Registry says the first proposed-deregistration notice is usually published about three weeks after it acknowledges receipt. If no objection is received within three months after that notice, the Registry publishes a further notice; the date of this second notice is the deregistration and dissolution date. Track the actual notices and company record, and follow Registry instructions if there is an objection or request for further information. Do not estimate a completion date from the filing alone. Companies Registry FAQ; Companies Registry pamphlet on deregistration
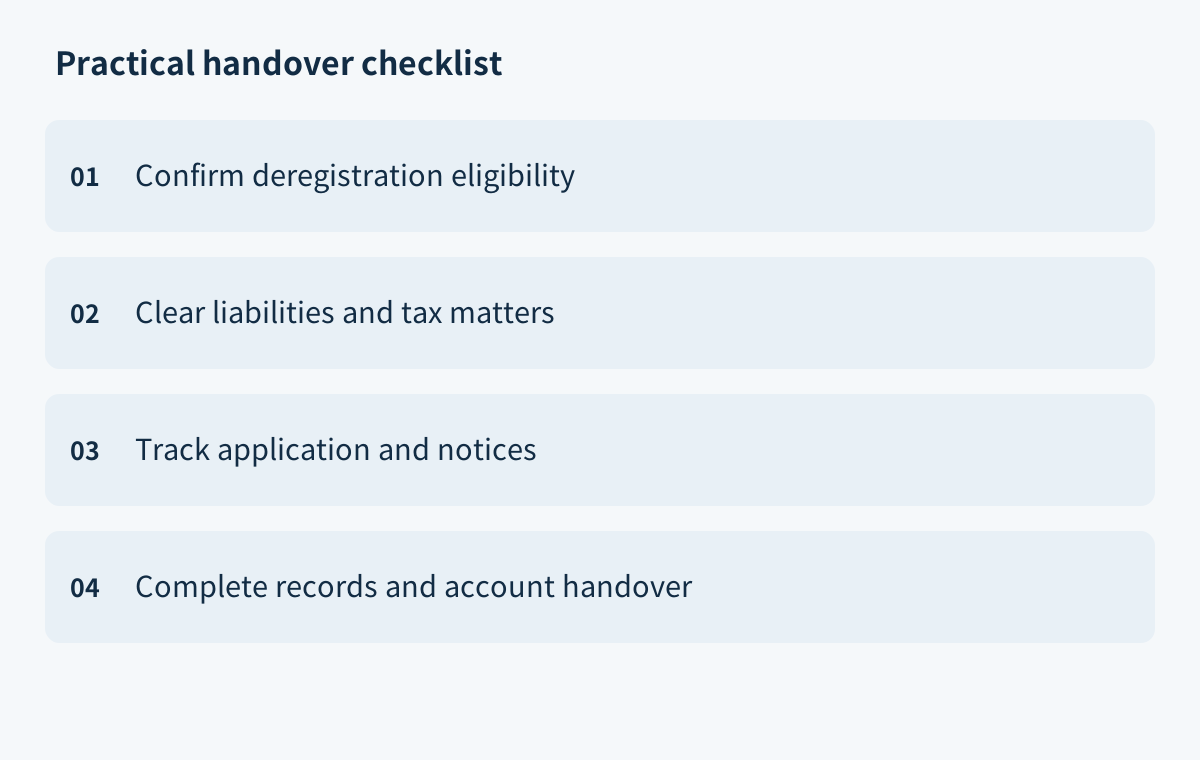
Use a tracking sheet for the notice issue date, NDR1 delivery date, Registry acknowledgement, first Gazette notice, objections or requests, subsequent notice and dissolution date. Link each entry to its notice, document index or Gazette record. Until dissolution, the company must continue to meet applicable statutory obligations, including filing annual returns. Submitting NDR1 does not end routine compliance. Companies Registry FAQ
Resolve bank accounts, contracts and records first
Treat bank and commercial arrangements as operational handover tasks; they are not steps prescribed by the Companies Registry’s deregistration process. Review company bank accounts, payment platforms, payment services, loans and credit facilities, customer refunds, supplier contracts, cloud subscriptions, domains and recurring charges. Ask each bank and counterparty what forms, settlements, authorised signatories, timing and final statements it requires. These details depend on the relevant terms and cannot be assumed from the general deregistration guidance. If payments or contracts involve Taiwan or other markets, confirm the relevant jurisdiction and currency. Assign a contact person to follow up and record confirmation dates and reference numbers.
Before closing an account, confirm who will handle incoming funds, refunds, taxes and payables. Download statements, transaction details and platform settlement records, and obtain termination confirmations. The company’s property must be dealt with before applying; the Registry includes bank credit balances among its examples. Do not assume that a balance can be claimed after dissolution. If funds remain or ownership is unclear, pause the filing and confirm the available treatment with the bank or a qualified professional before updating the asset schedule. Companies Registry deregistration service page
Create an index for member consent and directors’ resolutions, cessation evidence, accounts and tax records, tax correspondence, IR1263 and the Notice of No Objection, the NDR1 copy, delivery evidence, Gazette notices and search results, and bank and contract closure records. Note each item’s storage location, custodian and access rights. Confirm retention periods against applicable law, tax requirements, contracts and case-specific professional advice; there is no universal period stated here. If payments, employees or customer matters continue, identify who will take them over and when, before the company stops operating.
Verify dissolution and handle any remaining matters
Confirm that the company has actually been deregistered and dissolved. An NDR1 receipt, the tax notice or the first proposed-deregistration notice cannot establish that outcome by itself. Check the subsequent Gazette notice and company search record, and use the second notice’s publication date as the completion date. Save the official record in the company file and compare it with the original checklist: member approval, asset treatment, liability settlement, tax status, annual returns, bank closure and contract termination should each have an outcome and evidence. If the search status, notice date or documents do not match, ask the Registry to clarify before marking the matter complete.
Prepare a handover summary with the company name and number, dissolution date, key record locations, any remaining personal or contractual matters, the records custodian and contact details for relevant legal or accounting professionals. The Companies Registry pamphlet states that company property still held at dissolution vests in the Hong Kong SAR Government as bona vacantia. Recovering it requires an application to the Court of First Instance to restore the company; dissolution should not be treated as a way to defer asset disposal. Companies Registry pamphlet on deregistration
If an asset, creditor claim or other dispute emerges after dissolution, the response may involve restoration or other legal proceedings. Seek Hong Kong legal advice. A completed company search does not mean every historical responsibility has disappeared. For case-specific assessment, you may submit a question through the website contact channel. This article is general information, not legal or tax advice, and does not promise an outcome.