Published · Updated
When a Hong Kong company changes its activities, identify each affected record and its recipient. Inland Revenue Department (IRD) guidance requires written notice to the Business Registration Office within one month of a change in business nature; company name and registered office changes follow different arrangements. Government updates do not automatically reach banks, payment platforms or insurers, and the one-stop process covers specified company information only. Companies incorporated elsewhere must check filing rules in their place of incorporation. Whether licences, articles or other records need updating depends on the entity and its activities.
| Record or party | What to check | Evidence to retain |
|---|---|---|
| Business Registration Office | Details, change date and one-month notice | Copy, submission proof and updated record |
| Licensing authority or Companies Registry | Activity rules, licences and articles filings | Written guidance and filing result |
| Bank, platform or insurer | Required updates and effect on account or cover | Written confirmation or account record |
| External materials | Consistent entity details and approved versions | Version date, approver and sample check |
Business Changes and Company Name Changes Are Different
First identify which record is changing. The Companies Registry records the legal company name; a trading name, registered office, actual business address and business registration description serve different purposes. A website brand change does not change the legal name, and registering a new name does not automatically update the business description.
For a local Hong Kong company, the Registry and IRD offer one-stop notification for name or registered-office changes. A business-nature change requires a separate IRD notification. List the legal entity, each changed item, its current record and responsible authority; procedures may differ for a foreign company, branch or other organisation.
Maintain a log of old and new details, effective date, recipient, owner, evidence and status. Track simultaneous name, address and nature changes separately; one receipt does not prove all were processed. Match company and business-registration numbers, trading name and platform store name to the right entity, and give staff one approved version. Check the IRD’s one-stop notification guidance and guidance on changes to business registration details.
First Document the Actual Old and New Activities and Dates
Describe actual activity, not just website wording. Compare old and new products or services, customer types, transaction methods, delivery locations and payment arrangements. Build a timeline using contracts, orders, delivery and payment records, management decisions and public announcements. These help explain the change, but no single document always determines its legal effective date.
For example, a Taiwanese business might use a Hong Kong company to wholesale accessories overseas, then add cross-border online retail. Document each activity’s products, ordering, fulfilment, payment channels and actual start date before describing the change. This is hypothetical: a website launch, board meeting or first invoice is not necessarily the change date.
If activities overlap, record the period and status of each: already carried out, approved but not started, or under consideration. Keep date evidence and the responsible person. This prevents a budget, test plan or market research from being described as trading already begun. Document business lines separately rather than forcing them into one vague category. If unsure about the date or description, organise the facts, ask the Business Registration Office, and retain the question, submitted information and written reply.
Follow the IRD’s Notice Requirements and Deadline
Within one month after a business-nature change, notify the Business Registration Office in writing. Include the business registration number, business name, address, change details and date. Use form IRBR 193 or provide these details in writing. Submit online through GovHK or eTAX, by post or in person; fax is not accepted. Check the entity details and describe the actual change.
Submit under current official guidance and keep the full notice plus online confirmation, receipt or postal proof. Check the updated certificate or reply and correct errors as directed. Submission alone does not prove the record was updated. Verify separate procedures for a changed name or business address.
The one-month period applies to this IRD notice, not automatically to banks, payment platforms, insurers or licensing authorities. Keep it distinct from profits tax, income-source assessments and tax outcomes, which depend on transactions, records and applicable rules. If late or the date is disputed, promptly ask the IRD how to submit and retain its reply; do not replace the actual date with a website update date. Record submission date and method, check for completion evidence, and follow up with the Business Registration Office if the certificate is delayed or incorrect. See the IRD’s change guidance.
Check Licences and the Articles Separately
Business registration is not an industry licence or proof of compliance. For a new activity or delivery method, check licence, permit, qualification and prior-approval requirements by actual activity and operating location. For cross-border work, customer location, goods movement, service and performing party may matter. Confirm with the relevant authority or a qualified local professional. The IRD guidance notes some activities need separate licensing or recognised qualifications.
The articles are separate. A business-description change usually does not require amendment, but check restrictions and company objects. Some older memorandum provisions continue as articles provisions. One exception: a company holding a section 103 Companies Ordinance licence must state its objects while the licence remains in force.
For each possible licence, record activity, customer and location, direct involvement and start date; check the authority’s rules. If a summary is insufficient, provide a process diagram, contractual roles and product description and seek clarification before launch. For any amendment, confirm the resolution procedure, form and deadline. Registry guidance says articles amendments generally require a special resolution and filing; NAA2 may apply to company objects, while other changes may need another form. Check company type and articles, and seek company-law advice if needed. See the Registry FAQs and specified forms.
Update Banks, Payment Platforms and Insurers
Government updates do not automatically reach or satisfy banks, payment or collection platforms, marketplaces or insurers. Inventory active accounts and contracts; record the entity, account purpose, previously reported business, transaction locations, currencies and insured activities. Requirements and deadlines vary.
Ask each organisation through its official channel whether to report the change, which details and evidence are required, who submits them and when the update takes effect. For retail, subscriptions, collection of others’ payments or new products, explain ordering, fulfilment, money flows and start date. A certificate alone does not prove review is complete; do not report proposals as settled.
Ask about unsettled funds, limits, verification and insurance timing. Processes vary, so rely on the case-specific reply. Confirm verbal answers in writing. Track contacts, replies, documents, submission, status and next step; retain written confirmation, account records or official notices and submitted versions. If the activity may affect cover, confirm applicability before it starts. Keep unanswered matters pending: an IRD receipt or continued payments proves neither other records changed nor insurance still applies.
Keep Notices, Replies and Versions of External Materials
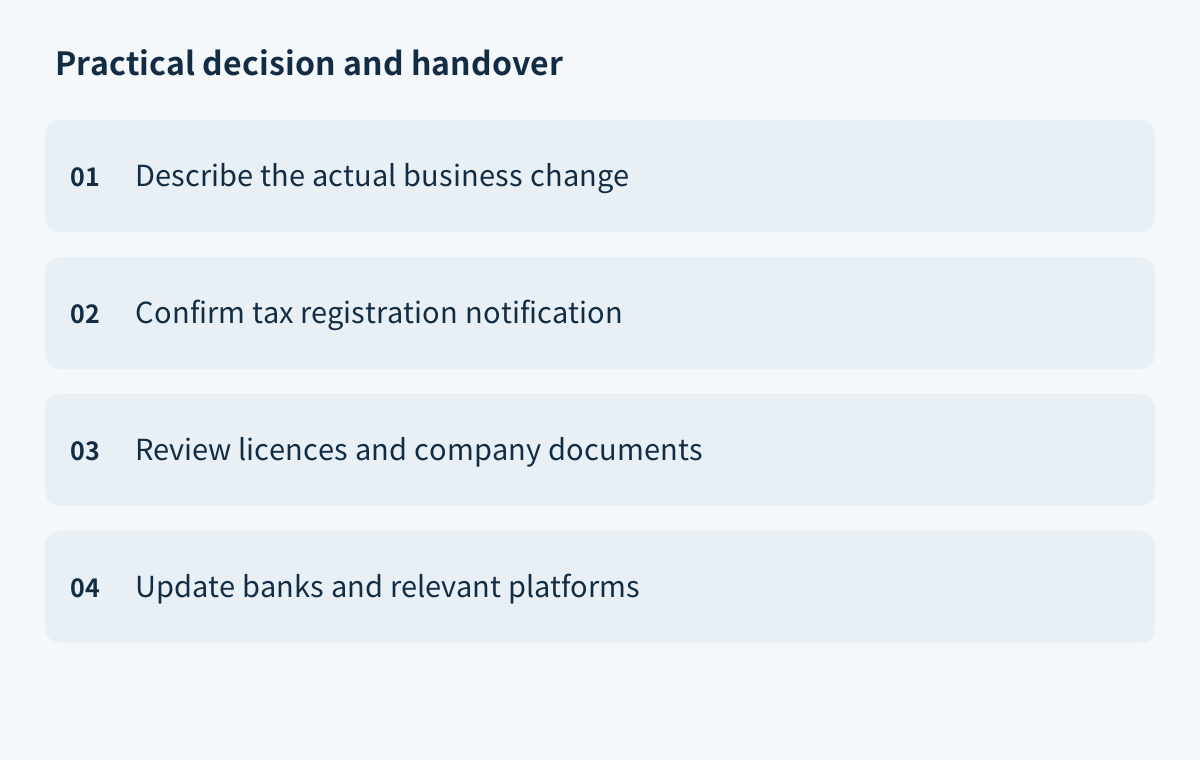
Keep a handover showing completed and pending updates. Save old and new descriptions, change date and evidence, the notice and submission proof, IRD replies or updated records, and correspondence with banks, platforms and insurers. This is internal tracking, not a statutory format or retention period; check separate accounting, tax and licensing record duties.
Track version date, owner and status for the website, quotations, contract templates, invoice details, platform merchant records and customer notices. Check that legal and trading names, business description, address and payment recipient agree. Sample sent documents and platform pages after updating. Mark new versions with an effective date and approver, retire old versions, and keep unconfirmed content in draft.
Confirm sales staff, accounting software and merchant accounts use the same entity name. Assign an owner and follow-up date to missing replies, document requests and insurance confirmations; keep them open until evidence arrives. For related reading, see the Hong Kong company annual filing and compliance calendar; it does not replace this notification. For a case-specific question, use the website contact channel. This article is not legal or tax advice and promises no result.