Published · Updated
Taiwan-based owners using a Hong Kong company for cross-border e-commerce, trade, SaaS or brand revenue can use a monthly close to make transactions, receipts and unresolved differences traceable. It supports daily decisions and reduces year-end reconstruction. This is an operating routine, not a universal statutory deadline; annual reporting, audit and profits tax work depend on company circumstances and the year’s notices. Examples use HKD; classify transactions from their records and applicable accounting treatment. For annual context, see Hong Kong Company Accounting & Tax Filing Guide. This article focuses on monthly records and handover.
| Workstream | Check | Keep |
|---|---|---|
| Sources | Bank and platform reconciliation | Statements and settlements |
| Transactions | Revenue, costs, receivables and payables | Documents and balances |
| Exceptions | Currency, prepayments, shareholder transfers | Evidence, owner and due date |
| Handover | Open items and closing balance | Trial balance |
What a Monthly Close and an Annual Audit Each Do
A monthly close reviews one period: record activity, reconcile bank and platform balances, and track receivables, payables and open items. It shows what happened, what remains unpaid or uncollected, and what evidence is missing. Set a regular date suited to transaction volume, follow consistent procedures and log late records; a close does not complete statutory filing or audit.
Annual statements summarize an accounting period; an audit examines the statements and underlying records. The Companies Registry says reporting-exempt companies may use simplified financial-statement and directors’ report requirements, but statements generally still require audit. Its stated audit exception is a dormant company. Reporting and audit exemptions differ. Companies Registry: Accounts and Audit
Before annual work, confirm the reference period, company and group structure, activity, director or shareholder decisions and formal dormant status. Eligibility depends on company type, group membership and size; revenue or staff numbers alone do not establish eligibility, nor does zero income establish dormancy. Hand over the trial balance or ledger, reconciliations, receivables/payables and open items; match closing to new opening balances, assign owners and dates for approvals, audit records and tax notices, and keep adjustment reasons and versions. Seek professional advice if unclear.
Gather Bank, Platform and Transaction Records
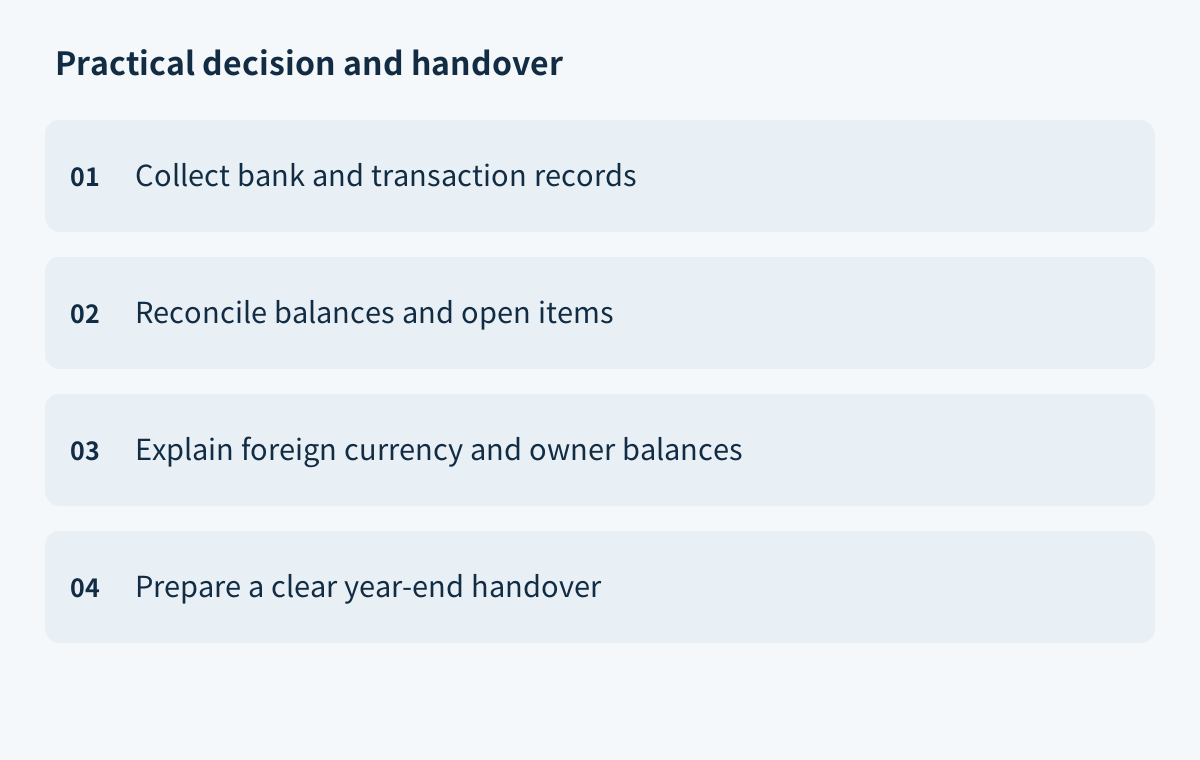
List each company bank account, payment platform and provider, with its currency and period. Confirm complete exports of statements, transaction details and settlements; identify multiple stores or receiving accounts separately. Check period dates and opening/closing balances for cross-month activity, delayed settlements and closed accounts.
Collect monthly bank statements; platform settlement and transaction reports; sales invoices/receipts; supplier documents; refunds, chargebacks, fees and reserve details. Record each file’s source, period, currency, download date and version. Preserve original exports separately from working copies, and log who supplied each document and when.
Do not count net platform deposits as sales revenue. Separate gross transactions, refunds/discounts, fees, chargebacks and held amounts; match settlement batches to bank deposits. The Inland Revenue Department (IRD) lists books, vouchers, statements, invoices, receipts, and asset and liability records. Goods businesses also need purchase, sales and inventory records; service businesses need evidence of services provided. IRD: Record Keeping
Reconcile opening balance plus inflows less outflows to closing balance, and platform net settlements to deposits. Log unavailable exports, closed access or screenshot-only records with the gap, substitute evidence and due date; do not replace originals with unsupported manual figures. Finish a source index and missing-record list.
Reconcile Revenue, Costs, Receivables and Payables
For each revenue item, link the order or contract, invoice, delivery or service record, platform transaction, settlement report and bank receipt. Note refunds, partial deliveries, instalments or platform collections by amount, date and reference. Use applicable policy and evidence—not deposit date alone—to determine period; flag incomplete records for review.
Link supplier invoices/receipts to purchase orders, delivery or service acceptance and payment. Retain inventory counts and movements. For equipment or long-term assets, keep invoice, business purpose, acquisition date and payment together. Note differing document, payment and delivery dates; bank debit alone does not set the cost period.
Receivables: customer, invoice number, currency, invoiced/received amounts, balance, due date and collection status. Payables: supplier, document, unpaid amount, due date and planned payment. Reconcile both to the ledger monthly; check cross-period receipts, duplicate payments, credit notes, refunds and unmatched deposits. Assign an owner and update date to each difference.
Hypothetically, HK$10,000 sales minus HK$200 refunds and HK$280 fees equals a HK$9,520 deposit. This arithmetic check is not a client case and does not decide classification. If the deposit differs, investigate reserves, chargebacks, foreign exchange or cross-period settlement, and retain evidence links.
Track Foreign-Currency Transactions, Prepayments and Shareholder Balances
Each foreign-currency record needs original amount/currency, transaction and settlement dates, actual bank debit/credit, fees and rate source. Keep bank conversion advice; do not retain HKD alone. Treatment may vary by date, settlement and reporting purpose. Log monthly facts, then have the annual accountant review conversion under policy.
For a prepayment, record payee, contract/order, date, original amount/currency, expected delivery and service period. Track delivered and outstanding portions monthly; payment does not prove completion. Keep evidence and expected date for undelivered items; link partial deliveries, multi-period subscriptions and refunds to the original payment.
For each shareholder transfer, record payer/recipient, company account, date, currency, purpose, relevant approval, and loan/repayment or contribution documents. Bank wording cannot establish loan, contribution, expense or distribution. Mark missing evidence unresolved and assign a follow-up owner.
IRD’s 2025/26 tips require specified BIR51 tax, depreciation-allowance and financial data in HKD. Its Notes require foreign-currency financial statements converted to HKD before filing, with the rate stated in the tax computation; this does not set one rate for daily transactions. IRD: 2025/26 Filing Tips; IRD: BIR51 Notes
Assign Owners and Dates to Open Items and Missing Records
Put unmatched transactions, missing documents and uncertain classifications on an exception list. Record each item’s period, transaction date, amount/currency, source account/platform, reference, difference, question, evidence location and follow-up owner. This distinguishes missing evidence, value mismatches, undelivered items and questions needing professional judgment.
For each open item, log request date, expected reply date, status, last update and review result. Specify the document and period requested; if overdue, note the reminder and next owner. For material items that may affect annual statements, record provisional impact and basis without presenting an estimate as confirmed.
At handover, separate reconciled items from those awaiting external records, internal confirmation or accounting judgment; identify provisional figures. If a refund lacks its order or an FX debit has no invoice, retain the transaction and enquiry history and request evidence rather than guessing. When records arrive, update the item with resolution, receipt date, reviewer and change history. Mark the period complete, complete with open actions or incomplete, and summarize outstanding counts, amounts and reasons. Refer unresolved tax or legal questions to an appropriate professional.
Hand Monthly Close Results to Annual Accounting and Tax Work
Confirm year-end, tax notices, required statements, supplementary forms, and preparer, reviewer and signer. Forms, methods and deadlines vary by assessment year, company and notice; follow IRD instructions and the actual notice. Monthly close does not replace annual statements, audit or tax filing.
Pack trial balance/ledger; bank/platform reconciliations; receivables/payables; foreign-currency calculations; prepayment/shareholder records; asset/inventory records; contracts, invoices and open items. Label period/currency/reference; tie closing balances to the ledger and include prior adjustment entries, reasons and approvals.
IRD’s 2025/26 tips say a paper BIR51 should include signed audited financial statements or a copy of signed accounts certified by a company director, principal officer or certified public accountant. Specified data must be in HKD. From 1 April 2026, persons specified under section 51AAB and Schedule 65 of the Inland Revenue Ordinance must e-file; semi-electronic filing is unavailable. Confirm company scope. IRD Filing Tips; BIR51 Notes
IRD’s general page says keep business records at least seven years; BIR51 Notes also refer to at least seven years after a transaction or until dissolution, if sooner. Requirements vary by company and record type; dissolution is no blanket basis for early destruction. Retain records and confirm before disposal. IRD Record Keeping
Keep sources, reconciliations, owners and open items clear. For case-specific questions, use website contact details; this is not legal or tax advice and promises no result.