Published · Updated
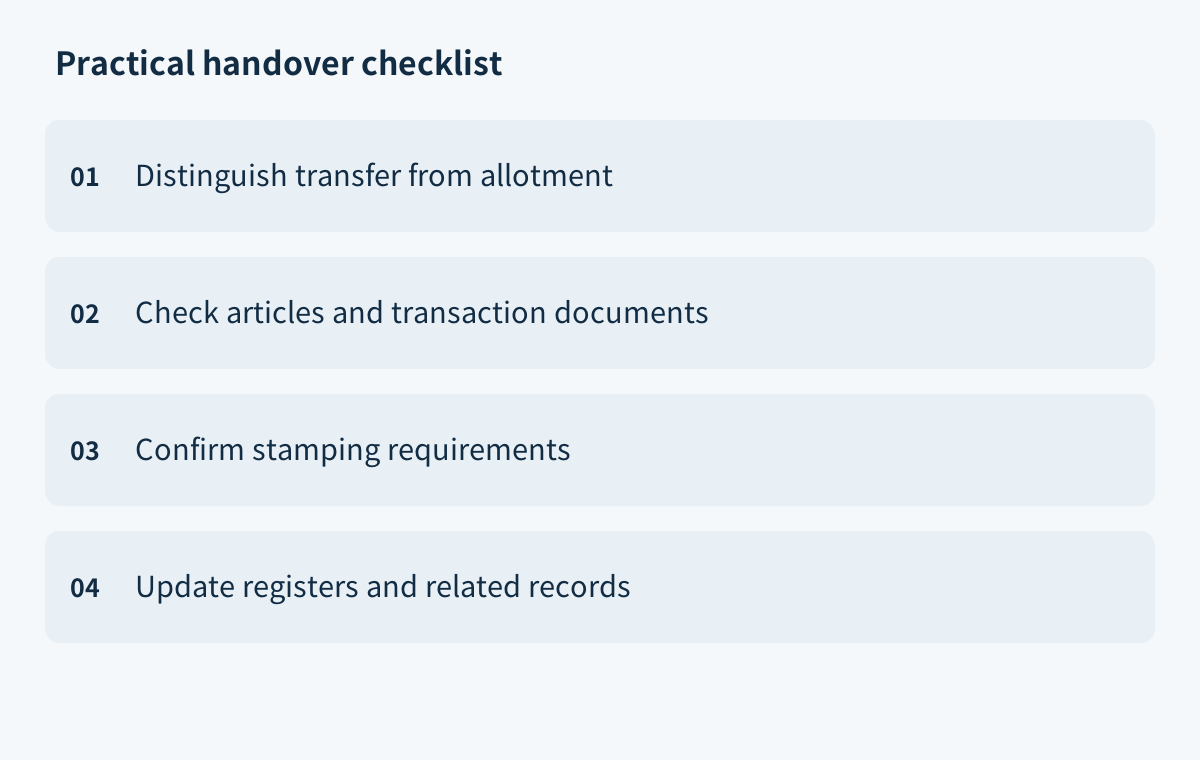
A Hong Kong share transfer involves more than changing a shareholder's name. First distinguish a transfer of existing shares from a new allotment, then check the company's articles and agreements, prepare transaction records, arrange stamping, update company registers and review beneficial ownership information. This guide assumes a direct transfer in an unlisted Hong Kong company limited by shares. Listed securities, different share classes, nominee arrangements, non-cash consideration and complex ownership chains may need separate analysis. The reader's location in Taiwan, mainland China or Malaysia does not change the Hong Kong law discussed here. This is general information, not legal or tax advice.
Distinguish a Share Transfer from a New Allotment
A transfer moves existing shares from one shareholder to a transferee; by itself, it does not increase the company's issued shares. An allotment is a new issue by the company to a subscriber and changes its share-capital records. If a deal includes both steps, document them separately. The person receiving payment alone does not determine the transaction type.
Record the company's name and type, current register of members, share classes and numbers, latest share capital, transaction method (sale, gift or other), consideration, parties and target completion date. For a partial transfer, calculate each holder's shares and voting rights before and after. For an allotment, separately identify the subscriber, share count and payment obligation.
A local Hong Kong company must file Form NSC1, the Return of Allotments, within one month after the first day of allotment. A transfer does not require an immediate notice to the Companies Registry; it is reported in the first Form NAR1 annual return made after the transfer. See the 1823 guidance on allotments and transfers and Companies Registry forms.
Use a transaction sheet to assign each step, document, owner and open question. Separately check rules for listed securities, employee plans, nominee holdings or a concurrent allotment.
Check the Articles and the Parties' Information
Obtain the current articles of association and review shareholder, investment and other agreements for transfer restrictions, pre-emption rights, notice periods, consent requirements, class rights and required waivers. Model articles do not prove which terms govern this company; resolve any mismatch with its records before proceeding.
Verify each party's legal name or company details, address, signatory and authority. Confirm any board or shareholder approval needed, and record the share class and number, price or other consideration, payment method, settlement date and existing certificate details. A sale, gift and other transfer may call for different documents. Bank or payment-provider identity checks are institution-specific, not a universal legal checklist for transfers.
Before signing, check that the transferor is the registered holder, the share details match, contractual conditions are met and signatories can bind their parties. Record conflicting registers or certificates, missing approval, or unclear nominee and control relationships as open items with an owner; do not treat them as approved or complete.
A pre-transfer checklist should connect each restriction to its source clause, required approval or waiver, evidence, responsible person and status. This gives directors, shareholders, records custodians and transaction parties a clear list of what remains before closing.
Prepare the Transfer Instruments and Sale Records
For a sale, assemble the sale agreement, transfer instrument, contract notes and payment or settlement evidence. IRD guidance says contract notes must state whether a party acts as principal or agent, the principal's name where relevant, transaction and note dates, stock and quantity, unit price and consideration, and settlement date. For an exchange, describe the property given in return. See the IRD's share-transfer stamping guidance.
A gift does not require sale contract notes, but its transfer instrument still needs stamping. No cash price does not by itself mean no duty: confirm the document type and assessable value. If the price is below market value on the transfer date, duty may be assessed on market value. For unlisted shares, the latest company accounts inform the valuation; the Stamp Office may request supplementary information.
Depending on company age, capital changes and the transaction, supporting material may include the articles or latest NAR1, an NSC1 for capital increases not reflected there, a certified sale agreement (or confirmation that none exists), accounts and other valuation records. Requirements vary; this is not a universal bundle.
Index files by name, version, signature status, date, custodian and purpose. The handover should show how the deal was agreed, shares and consideration were determined, approvals were recorded, settlement occurred and what remains missing.
Confirm Stamp Duty Steps and Deadlines
IRD deadlines depend on document type and where it is effected or signed:
| Document | In Hong Kong | Outside Hong Kong |
|---|---|---|
| Sale or purchase contract note | Within 2 days after the transaction | Within 30 days after the transaction |
| Gift transfer instrument | Within 7 days after signing | Within 30 days after signing |
| Other transfer instrument | Before signing | Within 30 days after signing |
Since 17 November 2023, each bought and sold note carries duty of 0.1% of the consideration or its value. At HK$1,000,000, each note is HK$1,000, or HK$2,000 together. This excludes duty on the transfer instrument and other amounts; a higher assessed value changes the total. A gift transfer instrument is HK$5 plus 0.2% of stock value; another kind is HK$5. See the current GovHK rates and IRD calculator.
Section 45 relief may cover qualifying transfers between associated bodies corporate. IRD describes a proposed 75% association threshold for instruments executed from 25 February 2026, subject to enactment, and an adjudication route. Verify current law and ownership conditions; a shared group name is not enough. See IRD intra-group relief information.
IRD excludes transactions involving derivatives or share swaps, debt as all or part of consideration, and adjustable consideration from online e-Stamping. Check the service scope and exceptions and use the Stamp Office's alternative process if necessary.
Track the document, trigger date, place, owner, due date, application and payment evidence, and stamp-certificate status together. Confirm unusual terms with the Stamp Office before a deadline.
Update the Register of Members and Share Certificates
Once stamping and transaction records are ready, reconcile them against the existing register of members. The company's records custodian should follow the articles and applicable requirements to record the former and new holder, share class, quantity and relevant dates. Reconcile totals so the transferor's reduction matches the transferee's increase and issued-share information remains consistent.
Check whether the old share certificate has been returned and should be cancelled or endorsed, and whether a replacement should be prepared under the company's documents. Keep the old certificate's disposition record and any new certificate copy or issue record, linked to the relevant holder and shares. This guide does not state a statutory deadline for a transfer certificate; verify the applicable requirement before setting a completion date.
Report the transfer in the first Form NAR1 annual return made after it occurs. The Companies Registry forms page lists NAR1 and Schedule 1 for members of an unlisted company. This filing does not replace the internal register update. If the instrument, stamp evidence or holder identity is unresolved, mark the change pending, not complete.
The handover should contain a before-and-after holdings summary, updated register, certificate records and NAR1 information still needed, each with status, date and storage location.
Connect Beneficial Ownership Records with Completion Evidence
Review direct and indirect ownership against the SCR tests: more than 25% of issued shares or voting rights; power to appoint or remove a majority of directors; or the right to exercise, or actual exercise of, significant influence or control. A trust or firm can create relevant control. See the Companies Registry's SCR FAQ; a direct name or percentage alone may miss indirect control.
Reassess if a person's shares, voting rights, director-appointment rights or actual control change. The SCR is kept at the registered office or another place in Hong Kong, not filed for registration. If kept elsewhere, Form NR2 is generally due within 15 days after it is first kept there or its location changes. Certain existing companies keeping it with the register of members may be excepted; check incorporation history and previous notices.
Banks and payment providers set their own KYC requests. They may ask for an ownership chart, shareholder or beneficial-owner identity, transaction documents, payment evidence or an updated register. These are institution-specific, not a common statutory list. Track what each institution has received, still needs or does not require.
The final file should contain signed instruments, approvals, settlement and stamp evidence, updated member and certificate records, before-and-after holdings, the SCR assessment and bank follow-up status. Mark handover complete only when records agree, evidence locations are clear and outstanding items are labelled. For a case-specific question, use the website contact page. This is general information, not legal or tax advice, and does not promise an outcome.